Transfer Pricing Valuation & IP Valuation for Cross-Border Transactions
Globally Certified (ABV®, ASA, CVA®, MRICS)
Valuation Experience
Valuations Completed
Industries Served
3-5 Days
When Intellectual Property Crosses a Border, the Arm's-Length Price Is Everything
Transfer pricing valuation determines the arm's-length consideration for transactions between associated enterprises. It becomes essential the moment a multinational group develops, transfers, licenses, or restructures intellectual property - and it sits at the intersection of valuation methodology, transfer pricing rules, and economic substance.
Transaction Capital LLC delivers independent transfer pricing and IP valuation for cross-border transactions spanning multiple jurisdictions. Our work supports intercompany IP transfers, technology licensing, royalty arrangements, business restructurings, and other related-party transactions requiring arm's-length economic analysis.
Every engagement is prepared and signed by a credentialed appraiser - not software, not a template, not a generalist.
Our Transfer Pricing & IP Valuation Services
Transaction Capital LLC delivers certified valuations for intercompany transactions, tax documentation, and cross-border restructuring.
Get a Documentation-Ready Transfer Pricing Valuation for Your Group Today.
Transfer Pricing & IP Valuation Methods We Use
Method selection follows the accurately delineated transaction, the reliability of available comparables, and the best method rule. Our credentialed appraisers apply the correct approach - and document exactly why.
| Approach | Best For | Key Methods | Formula |
|---|---|---|---|
| Market Approach | Transactions with reliable comparable third-party licenses | CUP, Comparable License Benchmarking | Value = Royalty Rate × Royalty Base |
| Income Approach | Unique or valuable intangibles with projectable economic benefits | DCF, Relief-from-Royalty, MPEEM | PV = FCF / (1 + WACC)^n |
| Cost Approach | Non-unique operational technology and internally developed software | Replacement Cost, Reproduction Cost | Value = Costs + Overhead − Obsolescence |
Relief-from-Royalty
MPEEM
With-and-Without Method
Transactional Profit Split
Cost Approach Limits
When Do You Need a Transfer Pricing or IP Valuation?
Specific Intercompany Events Trigger the Need for an Independent Arm's-Length Analysis
- IP Migration or Centralization - Moving ownership of intangibles between jurisdictions requires documented consideration.
- Intercompany Licensing - Royalty rates must be supported by comparability analysis, not industry averages.
- Business Restructuring - Converting to limited-risk distributors or contract manufacturers transfers value.
- Cost Sharing Arrangements - Platform contribution transactions require valuation under Treas. Reg. §1.482-7.
- Early-Stage IP Transfers - Uncertain outcomes may fall within the OECD's HTVI framework.
- Annual Documentation Deadlines - Local file, master file, and Section 482 documentation require valuation exhibits.
- Tax Authority Examination - IRS or foreign audits of intercompany pricing require defensible economic support.
- Advance Pricing Agreements - APA submissions require independent valuation of covered transactions.
- M&A Integration - Post-close consolidation of IP ownership creates new controlled transactions.
Not Sure If Your Transaction Requires a Valuation?
Who Needs Transfer Pricing & IP Valuation Services?
Transfer Pricing Valuation by Intangible & Transaction Type
| Intangible / Transaction Type | Typical Methodology | Key Consideration |
|---|---|---|
| Patents & Technical IP | Relief-from-Royalty, MPEEM, DCF | Remaining legal and economic life governs the benefit period |
| Software, Source Code & AI Models | MPEEM, DCF, Replacement Cost | Rights conveyed and development stage drive the conclusion |
| Trademarks & Marketing Intangibles | Relief-from-Royalty, With-and-Without | Territory, exclusivity, and brand maintenance obligations modeled |
| Know-How & Trade Secrets | Income Approach, Profit Split | Protection and confidentiality functions affect entitlement |
| Customer Relationships & Distribution Rights | MPEEM, With-and-Without | Attrition and contributory asset charges applied explicitly |
| Cost Sharing / Platform Contributions | Income Approach, Realistic Alternatives | Treas. Reg. §1.482-7 requires PCT valuation at buy-in |
| Business Restructuring & Function Migration | Profit Split, Realistic Alternatives | Transferred functions and opportunities require compensation |
| Hard-to-Value Intangibles | DCF with Probability Weighting | Contemporaneous assumptions and sensitivities must be documented |
Benefits of a Professional Transfer Pricing Valuation
Review Your Transfer Pricing Valuation
Before You Pay
Receive a complete draft of your arm's-length analysis and review the methodology, DEMPE conclusions, benchmarking, and sensitivity results before payment is due.
How Our Transfer Pricing Valuation Process Works
From Your First Call to Your Final Report - Simple. Fast. Defensible. Standard engagements are delivered in 5 to 7 business days after document receipt.
Free Consultation
Define the controlled transaction, entities, jurisdictions, terms, and timeline to receive a flat-fee quote.
Document Collection
Securely upload intercompany agreements, financials, projections, and IP schedules via our checklist.
Functional & DEMPE Analysis
Map the value chain, functions, assets, risks, rights transferred, and realistic alternatives.
Benchmarking & Modeling
Select the method, run comparability analysis, build the model, and test sensitivities.
Draft, Final Report & Support
Review the complete draft before payment. Examination support included at no charge.
What Your Transfer Pricing Valuation Report Includes
Every Report Is Built to Withstand Tax Authorities, Auditors, Advisers, and Counsel
- Executive Summary - Arm's-length conclusion, valuation date, and engagement scope
- Transaction Delineation - Controlled transaction, entities, jurisdictions, and contractual terms
- Functional & DEMPE Analysis - Functions performed, assets used, and risks assumed by each party
- Rights & Realistic Alternatives - Rights conveyed and the options realistically available to each entity
- Methodology Rationale - Best method selection and the alternatives considered and rejected
- Benchmarking & Comparability - Independent license evidence with documented comparability adjustments
- Financial Model - Projections, growth, margins, useful life, terminal value, and discount rate build-up
- Sensitivity Analysis - Impact of key assumption changes on the arm's-length conclusion
- Compliance & Signatures - Signed certifications (USPAP, IVS, SSVS-1) by credentialed experts
- Documentation Package - Supporting schedules, source logs, and management representations
Arm's-Length & Royalty Rate Requirements - What You Need to Know
Accurate Delineation
Functions, Assets & Risks
DEMPE Framework
Best Method Rule
Commensurate with Income
Comparability Adjustments
Contemporaneous Documentation
Compliance Standards We Follow
Most jurisdictions apply a form of the arm's-length standard, but statutory and documentation requirements differ. We build one consistent economic analysis, then address local requirements alongside your advisers and counsel.
IRC Section 482
IRS Revenue Ruling 59-60
ICPA SSVS-1
OECD Transfer Pricing Guidelines
OECD HTVI Approach
TIOPA 2010, Part 4
USPAP
IVS
Treas. Reg. §1.482-7
NACVA Professional Standards
Treas. Reg. §1.482-4
Insights From Real Valuation Engagements
2,500+ Valuations. 50+ Industries. Deep Expertise in Each.
Our Appraisers Understand Intercompany Value Chains and Intangible Economics - Not Just Generic Financial Models
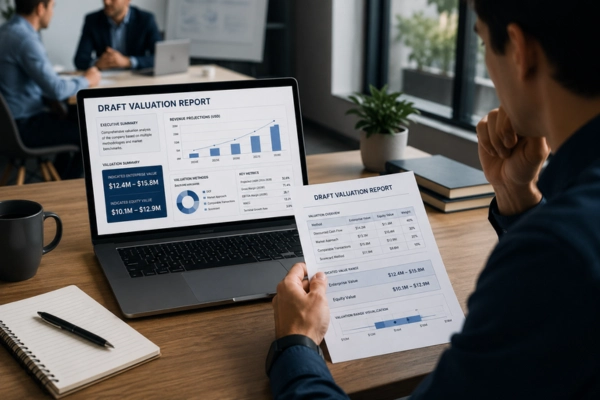
Review Your Transfer Pricing Valuation Before You Pay
Receive a complete draft of your arm's-length analysis and review the methodology, DEMPE conclusions, benchmarking, and sensitivity results before payment is due.
Trusted by Tax Directors, Advisers, Auditors, and Counsel
Multinational Tax Teams
Valuation exhibits aligned with Section 482, OECD, and local documentation rulesTax Attorneys & Counsel
Examination response, rebuttal analysis, and APA submission support
Transfer Pricing Advisers
Independent intangible valuation supporting benchmarking and economic analysisTax Attorneys & Counsel
Examination response, rebuttal analysis, and APA submission support
Thousands of Reporting Units. One Standard of Quality.
Join thousands of public companies, private acquirers, and portfolio businesses that rely on Transaction Capital LLC for goodwill impairment valuations that hold up when it matters most.




Do Not Take Our Word for It.
Transaction Capital LLC delivered a high-quality Fair Market Value (FMV) analysis with exceptional responsiveness, professionalism, and depth. The team communicated clearly throughout the process and provided strong transparency around their methodology, allowing stakeholders to understand not just the conclusions, but the rationale behind them.
The work delivered by TXN Capital LLC on the IVS 105 valuation for our deeptech startup demonstrates great quality. Their clarity in documenting assumptions and methodologies ensures transparency and ease of understanding.
Working with Gaurav at Transaction Capital LLC for our 409A valuation was seamless and professional. He delivered a thorough, defensible report quickly and explained every detail clearly. Highly recommend for any startup seeking a reliable and efficient valuation partner.
Transaction Capital LLC, led by Dr. Gaurav, is truly the best in the business valuation space. I’ve seen the results firsthand — working with anyone else would be a waste of money. Believe me, they are the best.
Gaurav is very knowledgable in his field and was super helpful in his response and explanations. He finished the contract well before the deadline! Highly recommended. Thanks Gaurav
We got the Financial Model made by Gaurav which included all the standard things. Gaurav was helpful in explaining all the complex lingos and make it simple for us to understand. Strongly recommend him for getting FM made
Best Transfer Pricing & IP Valuation Services in the USA
Transaction Capital LLC provides certified transfer pricing and intangible asset valuation services across all 50 US states and for cross-border groups worldwide. Headquartered in New York, with active engagements in Silicon Valley, Los Angeles, Chicago, Houston, Dallas, Atlanta, Austin, Boston, and beyond.